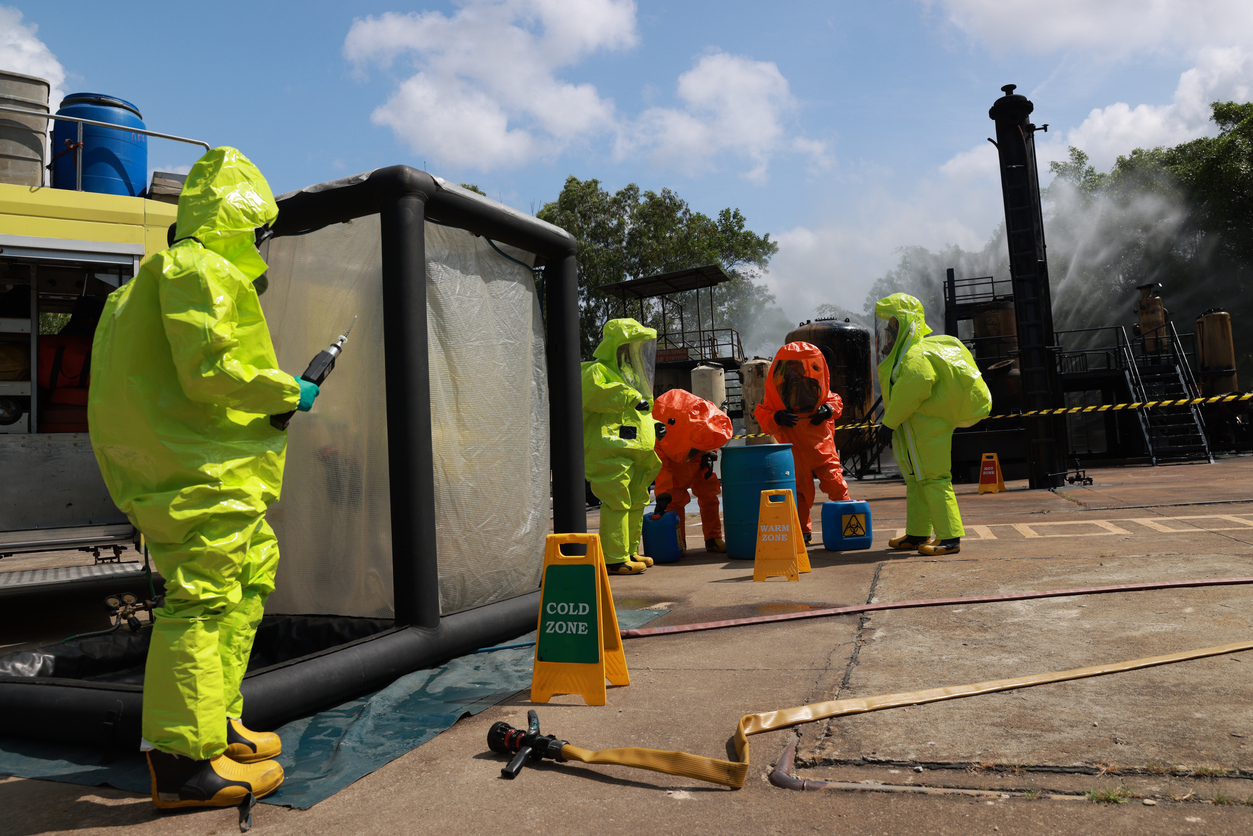
A groundwater client can have liability coverage in place and still leave an agent with important questions when contamination is discovered. A review of groundwater insurance should account for the client’s operations and consider when and where pollution could occur, including at job sites, during transportation, or after work has been completed.
What Should Agents Review for Groundwater Pollution Claims?
A groundwater pollution allegation can become complicated because coverage may depend on more than just the presence of contamination. Timing, location, the work performed, and the substance involved can all affect which policy provisions need closer review. A pre-claim review connects the facts of the exposure to the policy: When the alleged contamination occurred, where it occurred, what caused it, and which provisions apply to those circumstances.
Consider a groundwater contractor that completes work at a job site. Months later, testing identifies contamination, and the property owner alleges the earlier work contributed to it. An agent reviewing the claim would need to work through several questions before determining how the client’s insurance may respond.
When Did the Alleged Pollution Occur?
Timing can affect which parts of the insurance program come into play.
An allegation tied to active work may raise different questions than contamination discovered after the contractor has left the site. When completed work is involved, agents should review how the policy addresses completed operations and whether any applicable pollution coverage extends to incidents discovered after the work has ended.
Gradual contamination is an important consideration because the alleged release and the discovery of damage may occur at different times.
Where Did the Exposure Arise?
Groundwater businesses may face exposures at their premises, at customer job sites, or during material transport. WaterColor’s groundwater program, for example, identifies pollution coverage for gradual pollution and HAZMAT at insured locations, job sites, and in transit, subject to policy terms.
Agents should compare those circumstances with the client’s operations and policy language rather than assuming a pollution or general liability policy responds the same way in every location.
What Caused the Allegation?
An allegation could involve contamination from a substance encountered during groundwater work, damage connected to completed operations, or an error involving testing, recommendations, specifications, or other professional services. Each scenario may point agents toward different provisions within the client’s liability program.
The substance itself can also warrant closer review. The U.S. Environmental Protection Agency identifies bacteria and heavy metals, including arsenic and lead, among potential private well contaminants. Research in the western Great Basin has also documented elevated arsenic in groundwater wells.
What Should Agents Ask Before a Groundwater Pollution Claim?
Every renewal, new submission, or change in operations creates an opportunity to work through the exposure before a claim occurs. Ask about:
- Operations: What groundwater services does the client perform?
- Location: Could pollution be alleged at the client’s premises, at a job site, or during transportation?
- Completed work: Could contamination be discovered after a project has ended?
- Contaminants: Does the client handle or encounter arsenic, lead, radon, bacteria, or other substances?
- Pollution terms: Does the policy address gradual pollution and other pollution exposures associated with the operation?
- Other liability: Could the work create professional liability, products liability, or completed operations exposures?
- Policy terms: Do the limits, exclusions, and conditions reflect how the client operates?
Agents reviewing related water-industry accounts should also watch for pollution liability gaps that may become apparent only after examining the policy beyond its coverage labels.
Review Groundwater Exposure Before a Claim
Reviewing groundwater insurance means matching the policy to the work the client performs and the ways a pollution allegation could develop. Working through the when, where, and what of the exposure before an incident gives agents a clearer basis for identifying questions that need to be resolved.
If a client’s current program leaves unanswered questions, get in touch with WaterColor Management to discuss insurance options for groundwater operations.
About WaterColor Management
WaterColor Management has insured the water industry for over 30 years. Our policies include unlimited defense cost coverage in the event of a lawsuit against you. Call us at (855) 929-0824 or email info@watercolormanagement.com for a quick quote for your Water Business Professional, Products/Completed operations, Pollution, and General Liability Insurance.