A client may carry general liability and still have exposures that require a closer look. When reviewing water treatment insurance, agents need to compare the policy’s exclusions with the business’s actual work. An exclusion becomes a potential coverage gap when it conflicts with an exposure created by the client’s services, materials, work locations, or completed operations.
In the water treatment industry, one client may distribute treatment chemicals; another may service cooling systems, test water, install equipment, or provide consulting services. The same exclusion will not carry the same significance for every account.
Which Exclusions Deserve a Closer Look?
Consider a company that supplies treatment chemicals and services equipment at customer locations. Instead of working down a generic list of exclusions, start by following the company’s work from the warehouse to the job site and beyond.
What Does the Business Handle?
Chemical-related and contaminant exclusions deserve scrutiny when a client blends, sells, transports, or uses treatment chemicals. The substances involved can vary with the work. For example, chemicals may be added to cooling tower water to control corrosion and biological growth.
Agents should identify the materials involved and look for policy language addressing pollution, corrosives, HAZMAT, or other relevant substances.
What Happens at the Customer Site?
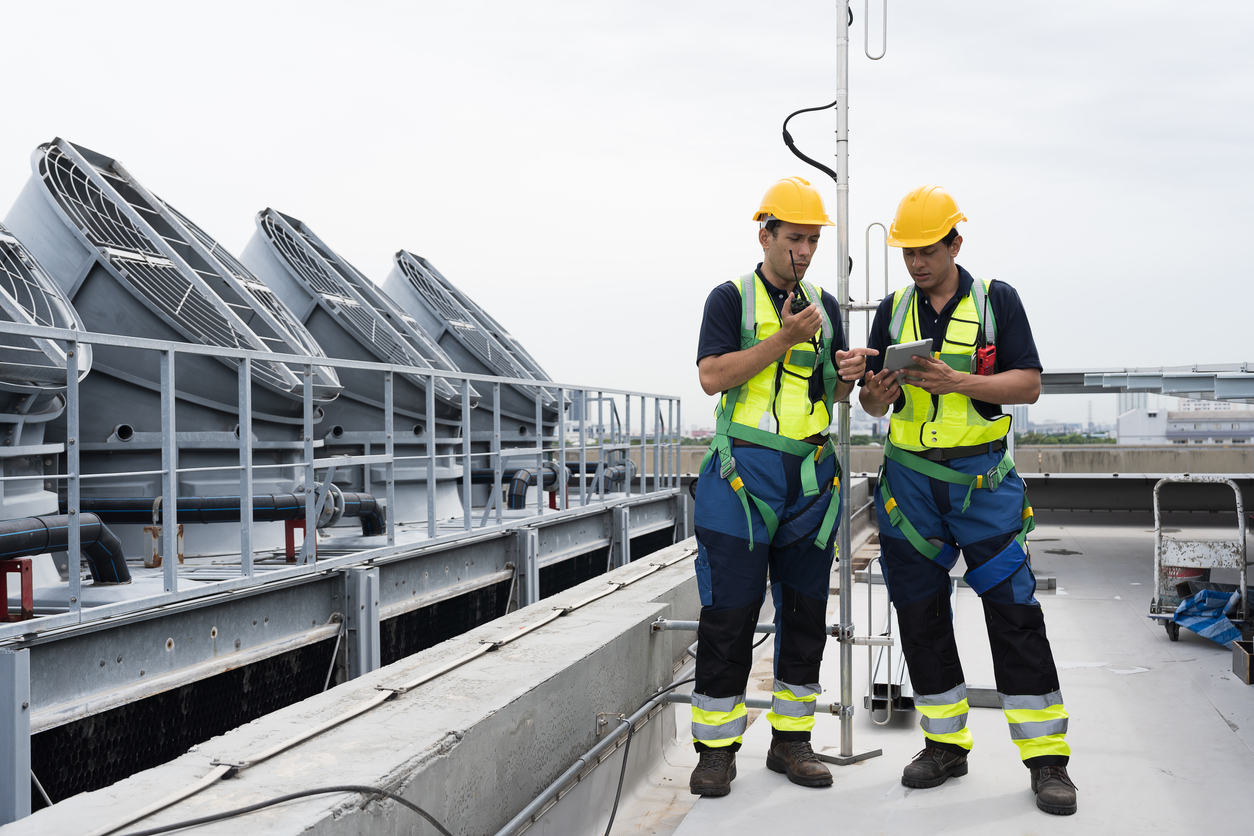
Servicing equipment can introduce a different set of questions. A client working on cooling systems, for example, may encounter both microbial and chemical exposures. Legionella can grow in cooling towers when conditions allow, so agents reviewing accounts that service these systems should check how the policy addresses bacteria-related exposures.
Location matters, too. Agents should determine whether exclusions or limitations change when an incident occurs at the insured’s premises, a customer location, a worksite, or during transportation.
What Could Surface After the Work Ends?
The exposure does not necessarily end when the technician leaves. A customer could later allege contamination following treatment work, a problem with a supplied product, or an error connected with testing or consulting.
Completed operations, products liability, professional liability, and pollution provisions may all become relevant depending on the allegation and policy wording. The better question is not whether the client “has” each coverage by name. It is whether an exclusion or limitation prevents the policy from addressing an exposure created by the client’s work.
WaterColor’s program illustrates the distinction. Its water treatment policies specifically state that they do not contain standard industry exclusions for mold, Legionella and other bacteria, corrosives, and certain other contaminants. The program also addresses HAZMAT and pollution exposures at insured sites, job sites, and during transportation, subject to policy terms.
What Should Agents Review Before Placing Coverage?
A review starts with the account rather than the declarations page:
- Services: What treatment, servicing, testing, consulting, installation, or other work does the client perform?
- Materials: What chemicals, products, contaminants, or hazardous substances does the business handle?
- Locations: Where could an incident occur?
- Timing: Could a claim arise after work ends or after a product reaches the customer?
- Policy language: Which definitions, exclusions, endorsements, conditions, and limits affect those exposures?
A previous review of pollution liability gaps in water treatment programs can help agents identify additional policy details that need attention.
Keep Coverage Aligned With the Risk
The goal is not to find a water treatment insurance policy with no exclusions. Agents need to determine whether the exclusions that are present conflict with what the insured handles, where employees work, what services the business provides, and when a claim could surface.
Reviewing those connections during quoting and renewal gives agents an opportunity to identify potential gaps before a loss puts the policy language to the test. Call WaterColor Management today to discuss coverage for a water treatment account.
About WaterColor Management
WaterColor Management has insured the water industry for over 30 years. Our policies include unlimited defense cost coverage in the event of a lawsuit against you. Call us at (855) 929-0824 or email info@watercolormanagement.com for a quick quote for your Water Business Professional, Products/Completed operations, Pollution, and General Liability Insurance.